
Savings and credit cooperatives in Ethiopia are preparing to expand into investment activities following the approval of the Cooperatives Proclamation No. 1416/2026 in May, although financial constraints, lending risks and regulatory requirements remain key challenges.
The proclamation allows savings and credit cooperatives to engage in investment alongside their regular savings and credit services. Nearly six months after its approval, cooperatives are assessing potential investment opportunities and developing plans to take advantage of the new legal framework.
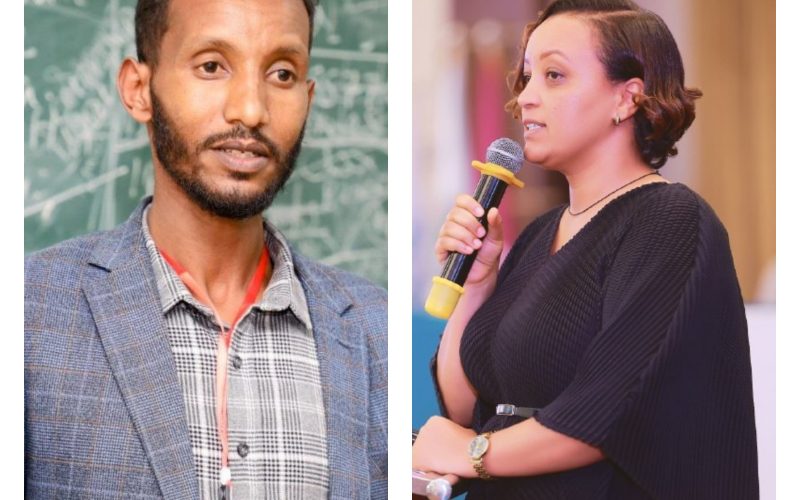
Tesfa Tibeb, marketing and business development manager at the newly established Bright Savings and Credit Basic Cooperative, said the institution was fulfilling the requirements needed to enter the investment sector.
He said the cooperative’s growth over the past two years, along with its performance in mobilizing savings and distributing loans, had encouraged it to consider investment opportunities.
“The main stage we are currently in is the feasibility study,” Tesfa said, explaining that an advisory committee under the executive committee was identifying viable sectors.
Under the proclamation, cooperatives are expected to limit their investment participation to 60%, with the remaining 40% provided by private investors. Bright plans to follow this arrangement if its proposed investments receive approval.
The advisory committee will submit the feasibility study to the executive committee before it is presented to the general assembly for a final decision. The general assembly, as the cooperative’s highest decision-making body, must approve the proposal before implementation.
However, Tesfa identified several challenges that could limit cooperatives’ ability to invest. These include inadequate savings mobilization among members, delayed loan repayments and the difficulty of securing private investors willing to provide the required 40% share.
He warned that reliance on external investors could also create trust-related concerns as cooperatives seek partners for their investment plans.
Tigist Garomsa, Head of the CEO office of Awach Savings and Credit Cooperative, said her institution had long advocated for changes to the law to allow cooperatives to invest their accumulated resources.
Awach has historically relied on income generated from members’ savings and has explored investment opportunities that were previously restricted under the legal framework, she said.
“We do not have a liquidity problem now. The new proclamation will improve our relationship with other institutions. It will also help us obtain additional resources,” Tigist said.
She said Awach was assessing potential investments in the hospitality, health and education sectors and preparing feasibility studies and business plans.
The cooperative is considering several financing options, including using its own resources and selling shares to its members. She said the institution had previously received proposals to collaborate with car importers but had not pursued them, partly because the former legal framework did not permit such arrangements.
With the new proclamation allowing partnerships with investors, the cooperative is now reviewing opportunities that could help it diversify its activities and generate additional income.
Tigist said purchasing shares from existing members was among the options under consideration.
Bedlu Melsew, executive director of the Financial Cooperative Development Department at the Ethiopian Cooperative Commission, said cooperatives had long requested permission to invest, citing their growing deposits and financial resources.
He said the new proclamation was intended to enable financially capable cooperatives to diversify their activities and generate additional wealth while protecting members’ savings.
Bedlu explained that the 60% cooperative and 40% investor arrangement was designed to prevent cooperatives from committing excessive resources to investment at the expense of their core savings and credit services.
He acknowledged concerns that the arrangement could create difficulties in finding suitable investment partners but said outstanding implementation issues would be addressed through additional regulations and guidelines.
According to the proclamation, cooperatives cannot invest more than 10% of their total assets, and members’ savings cannot be used directly for investment.
He said the implementing regulations had been reviewed by the Ministry of Agriculture and the Ministry of Justice and submitted to the Council of Ministers for approval.
The new framework could create opportunities for cooperatives to diversify their income sources and expand their services. However, the impact will depend on their ability to mobilize savings, maintain sound loan-repayment rates, identify viable projects and secure reliable investment partners.
According to the Federal Cooperative Commission, Ethiopia has more than 90,000 cooperatives with total assets exceeding 65 billion birr.Savings and credit cooperatives play a role in expanding access to savings and loans, particularly for households and businesses that face barriers to conventional financial services. Allowing them to invest could broaden their economic activities, but regulators face the challenge of encouraging growth without exposing members’ funds or weakening the institutions’ core services.
Source:- Capital newspaper
